Investors have largely overlooked European small-cap companies in recent times. Francisco De Juan suggests current valuations make a compelling case to include these organisations in portfolio allocations.
For much of the past decade, the world’s capital has had somewhere better to be. It flowed, year after year, into American technology and the machinery of passive money that carried it. European small-cap companies became the market global investors learned to do without.
Part of that neglect was deserved. Europe has been marred by overregulation, persistently insufficient defence spending and an energy policy that resulted in dependence on unreliable partners. Surging geopolitical turbulence has affected the Old Continent more acutely than others – the latest conflict in the Middle East is stark evidence of this.
Although since the invasion of Ukraine, Europe has woken up and is correcting course, the discount in European equity valuations persists. Easing tensions and the prospect of a reopened Strait of Hormuz should be a clear catalyst to reduce the double discount in European small caps.
These valuation discounts have remained hidden in plain sight and the opportunity to close them has rarely been greater.
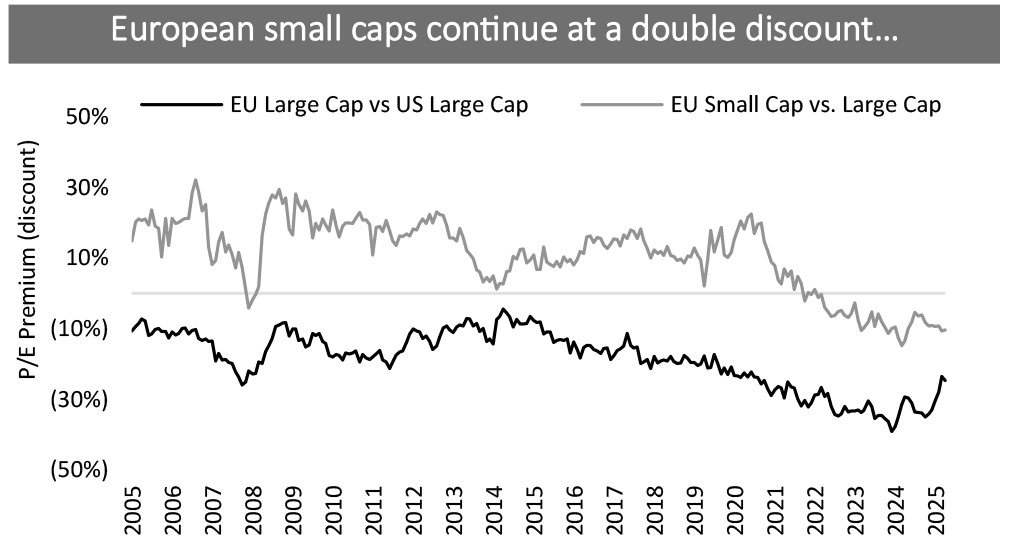
A double discount, hidden in plain sight
Europe trades at a deep discount to the United States. Historically in the range of 10 per cent to 15 per cent, this gap has widened to close to 25 per cent. Within European small caps, the dislocation is even higher: while historically valued at 15 to 16 times earnings, they are marked today at 13 to 14 times. United Kingdom small caps, suffering from the long tail of Brexit, high interest rates and an uncertain political future, trade at roughly nine times 2026 earnings.
But the factors that underpinned the European discount are changing. A continent that let its defences lapse is rearming. One that surrendered its energy security is working to reclaim it. One that struggled to act as a single body is, slowly and unevenly, finding reasons to do so. None of this will be quick, Europe rarely is, and the recent turmoil in the Middle East might have slowed down the process. But the direction of travel has changed and that is what matters most.
European pessimism today has become a habit, but habits are subject to change as the factors that initially created them evolve. The continued gloom scenario doesn’t match the positive progress that the quiet leaders in their sectors have made. Over the past five years, many have generated strong real cash flow and high returns on capital employed. What has been suppressed is not their quality, only their recognition.
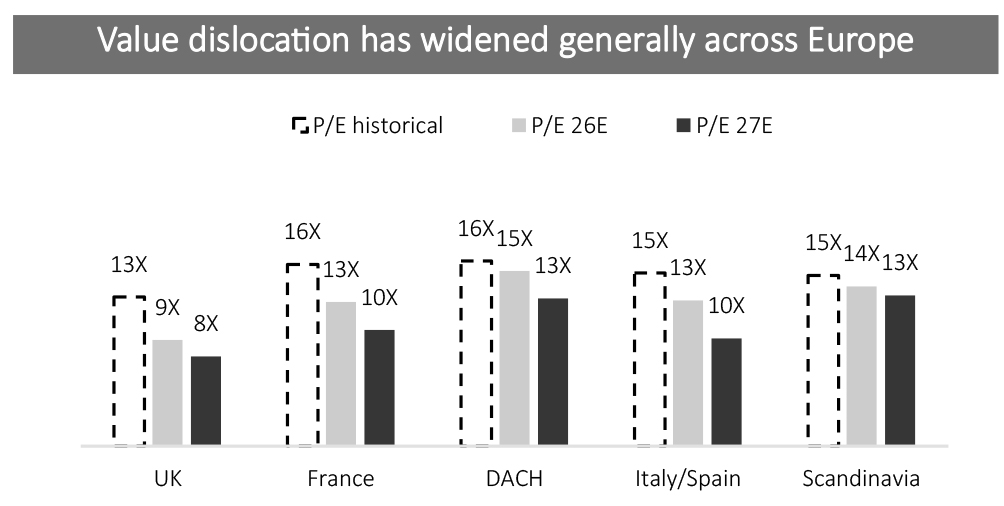 Source: Bloomberg as of 31.03.2026. Relative performance index based on P/E 12-month forward differentials between MSCI Europe LC vs S&P 500 Index and vs. MSCI Europe Small Cap.
 Notes: i) Price to positive earnings; ii) UK P/E of FTSE small cap; iii) French MSCI SC; iv) DACH P/E average of the German SDAX, the Swiss MSCI SC and the Austrian MSCI SC; v) Italy/Spain is avg. P/E of Italian ITSTAR and Spanish IBEX small cap; and vi) Scandinavia is avg. P/E of Swedish MSCI SMID and Nordic MSCI SC. Source: Bloomberg, EQMC.
The real opportunity: not just cheap, but fixable
Most investors have their wealth close to home, concentrated and in familiar domestic names. In today’s European small-cap equity market you can demonstrate to an investor that the opportunity is most likely complementary, has nothing to do with their portfolio, which cannot be bought at home at any price, and, more importantly, it doesn’t solely rely on Europe being reborn. It rests on something simpler and more durable: that good companies can trade for less than they are worth and a patient, engaged owner can help close the gap. The question was never whether these companies are cheap. They are. The question is who will do the work so the price reflects what they are truly worth.
That, in the end, is what we do. For more than 20 years EQMC has invested in Europe’s smaller companies with what we have always called a public market’s approach and a private market’s mindset. Taking sizeable stakes, typically 10 per cent to 20 per cent, large enough to earn a place on the board, in businesses that are not broken but merely overlooked, undermanaged, under-governed or simply unnoticed. The gap between what such companies are and what they could become is not a flaw in the market to be lamented: it is the opportunity itself.
Three companies, three routes to value creation
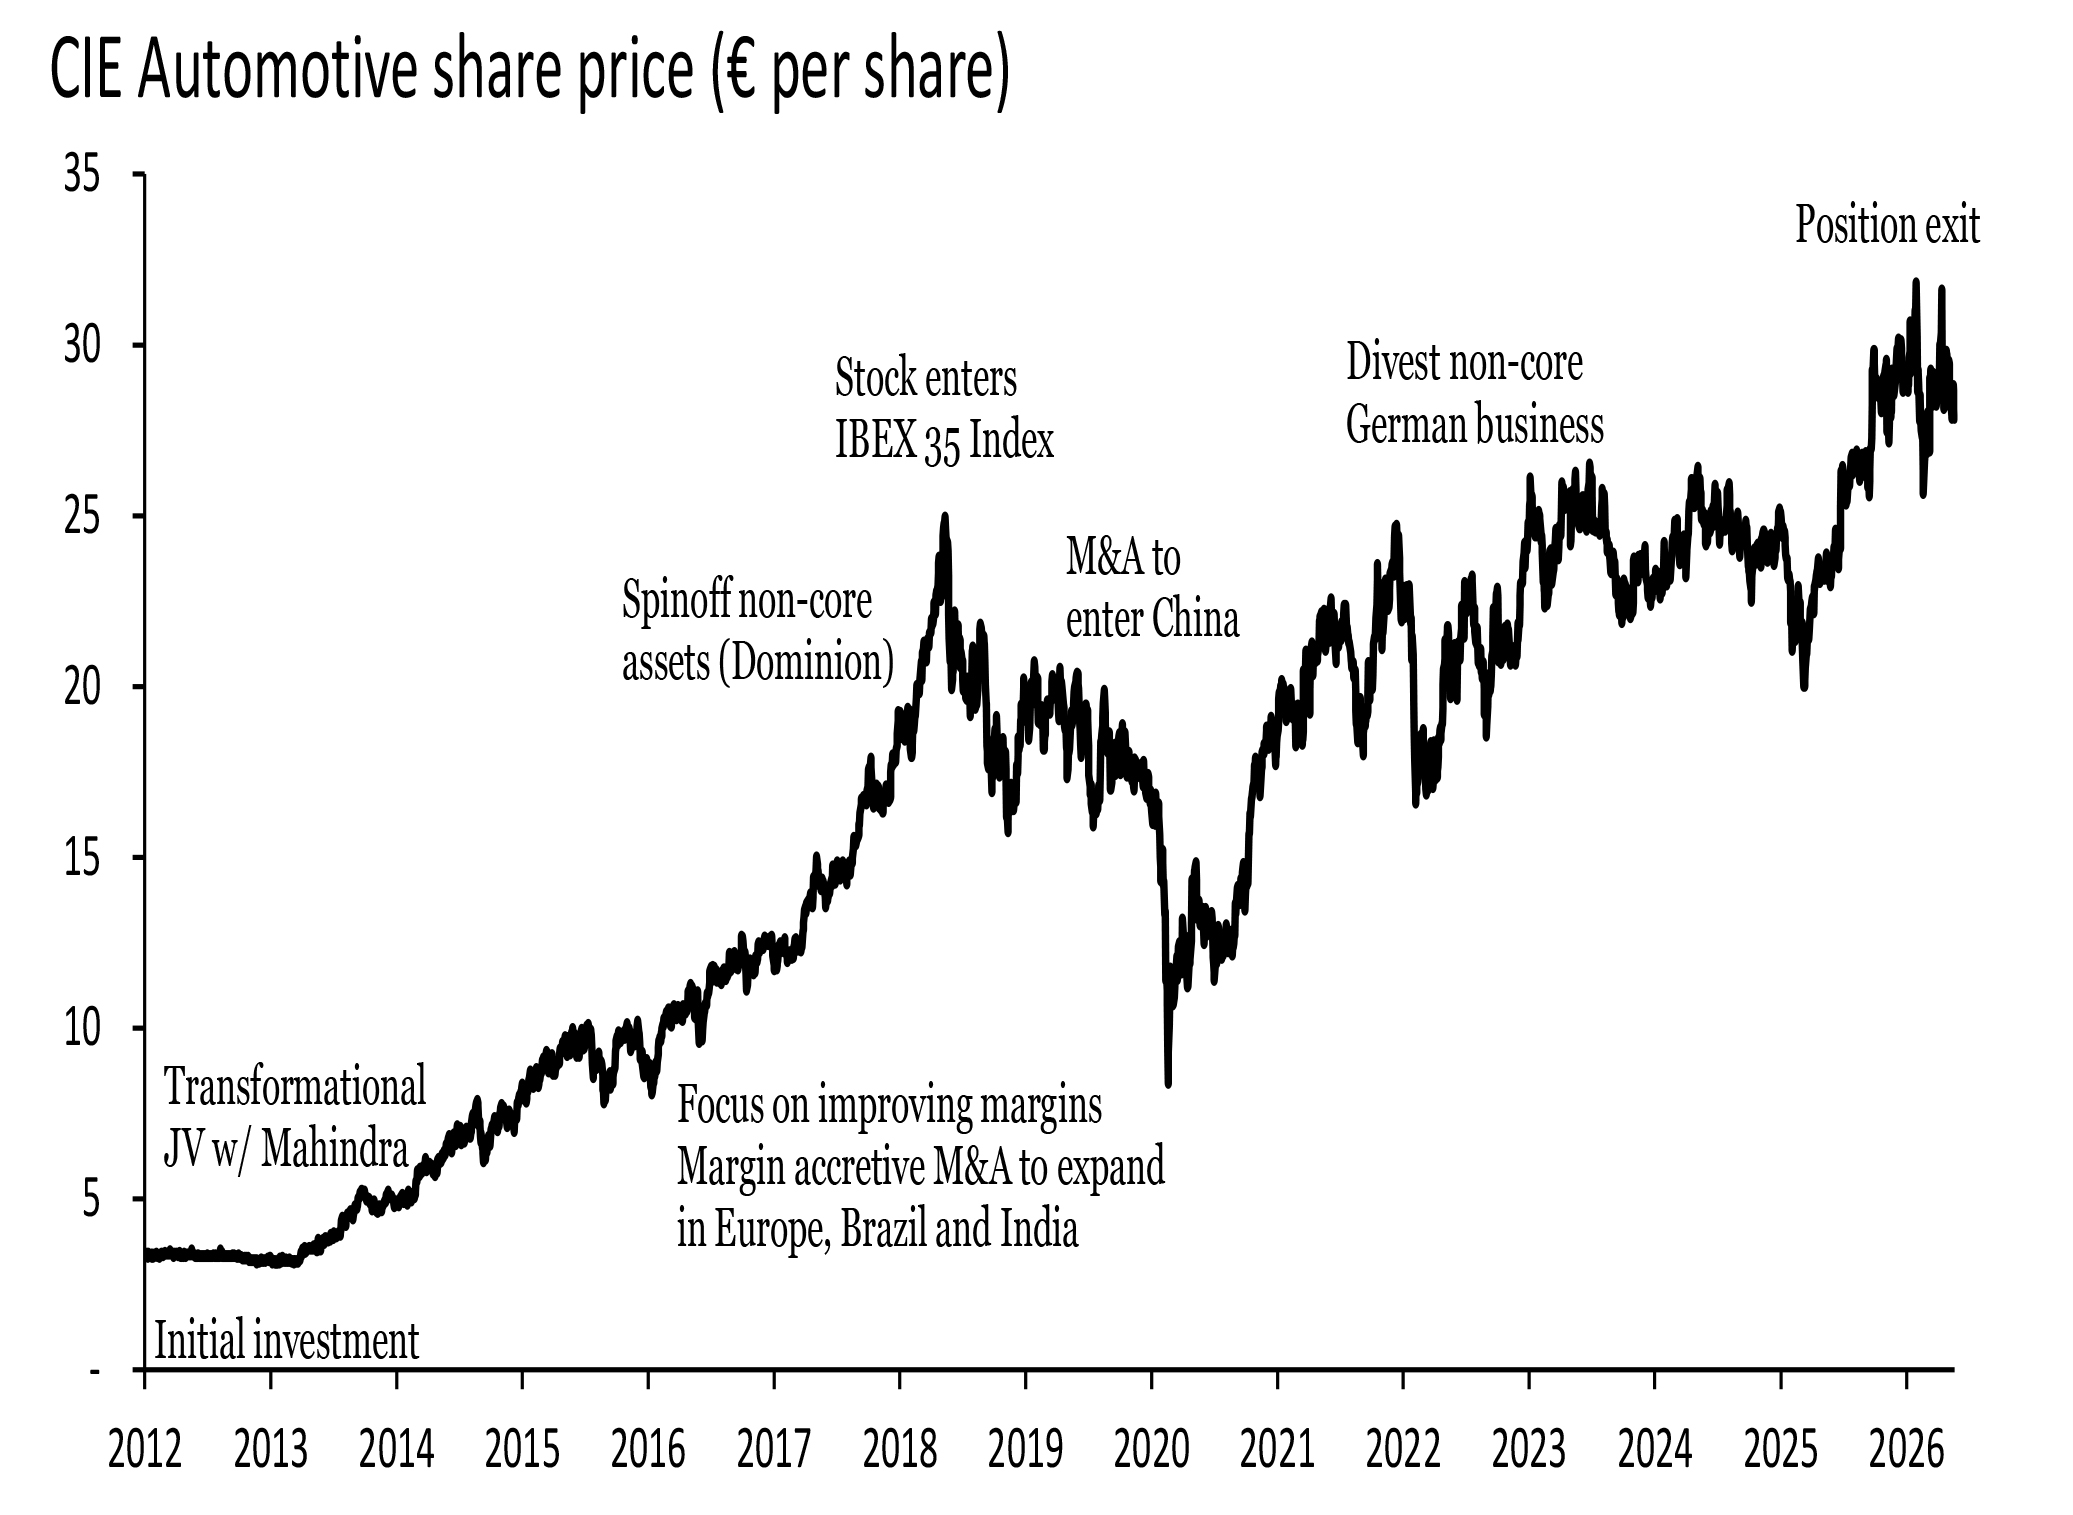
When we invested in CIE Automotive in 2012, it was then a EUR500 million Spanish maker of precision components, capable but inward looking and tied almost entirely to its home market. We saw a management team with the discipline to build something far larger and the rigour to do it profitably. Over the decade that followed, we worked beside them on capital allocation, structure and acquisitions as CIE bought carefully across Europe, the Americas and Asia and shed the divisions that no longer earned their keep, until it stood as the lowest-cost, highest-margin operator in its field. By the time we sold in 2026, it had compounded at more than 20 per cent a year, grown sixfold to over EUR3 billion, and managed to take its place in Spain’s IBEX 35 Index at one point. A forgotten domestic small cap had become a global mid-cap. That is the journey in its purest form.
 Source: Bloomberg (price data adjusted for spin-offs and dividends)
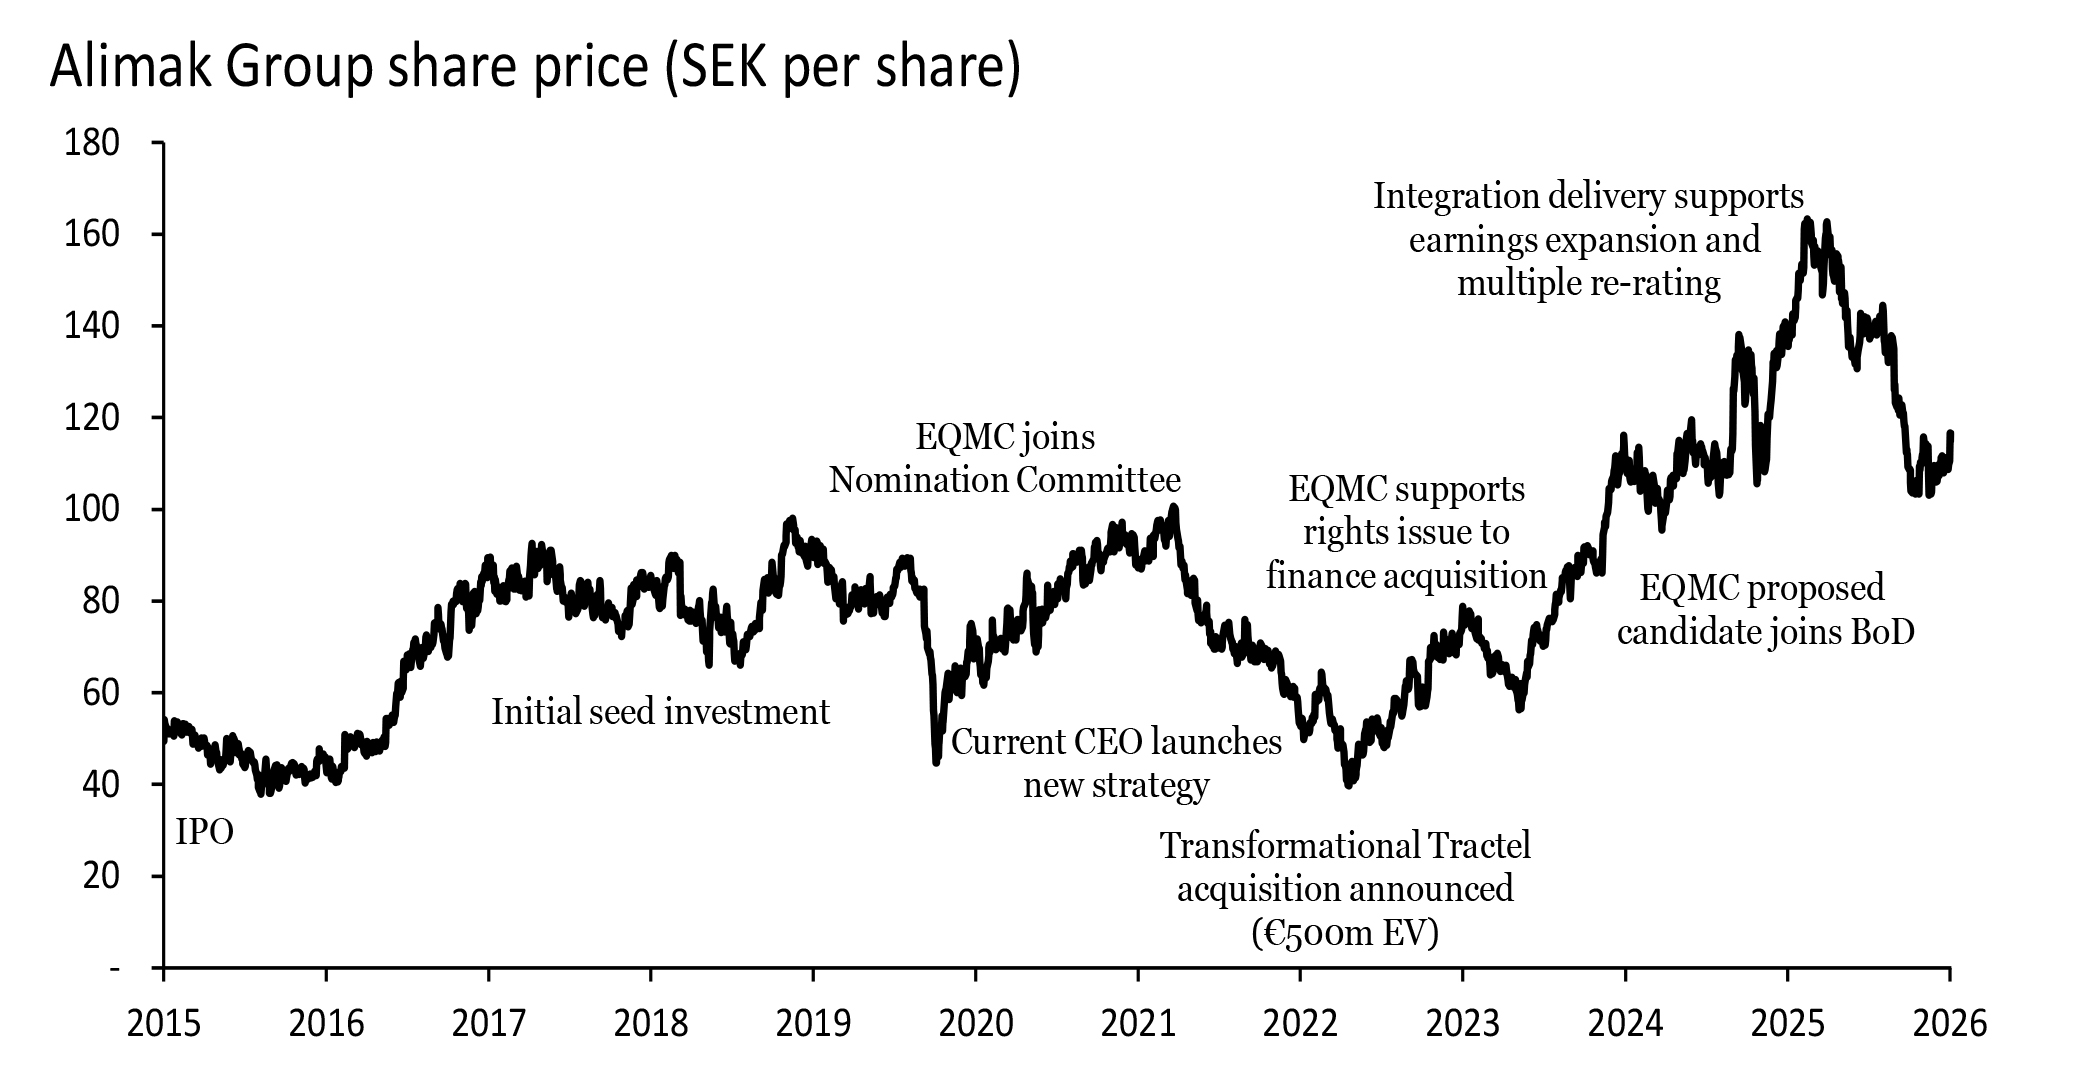
Alimak, the Swedish maker of the industrial hoists that climb construction sites, wind turbines and refineries the world over, offered something different. Beyond the machines, it earns a steady, recurring income servicing an installed base that only grows – a quality its plain industrial label disguises. We invested in 2017 and spent years making the case, to management and fellow owners alike, for consolidating a fragmented market. In 2022, the groundwork paid off: alongside Latour, the company’s largest shareholder, and other major owners, we helped fund and stood behind the acquisition of Tractel, its principal global rival. The effect was immediate and permanent: Alimak became the outright leader in its field, with better margins, clearer earnings and at last a valuation worthy of this great business. One deal, years in the making, changed everything.
 Source: Bloomberg (price data adjusted for spin-offs and dividends)
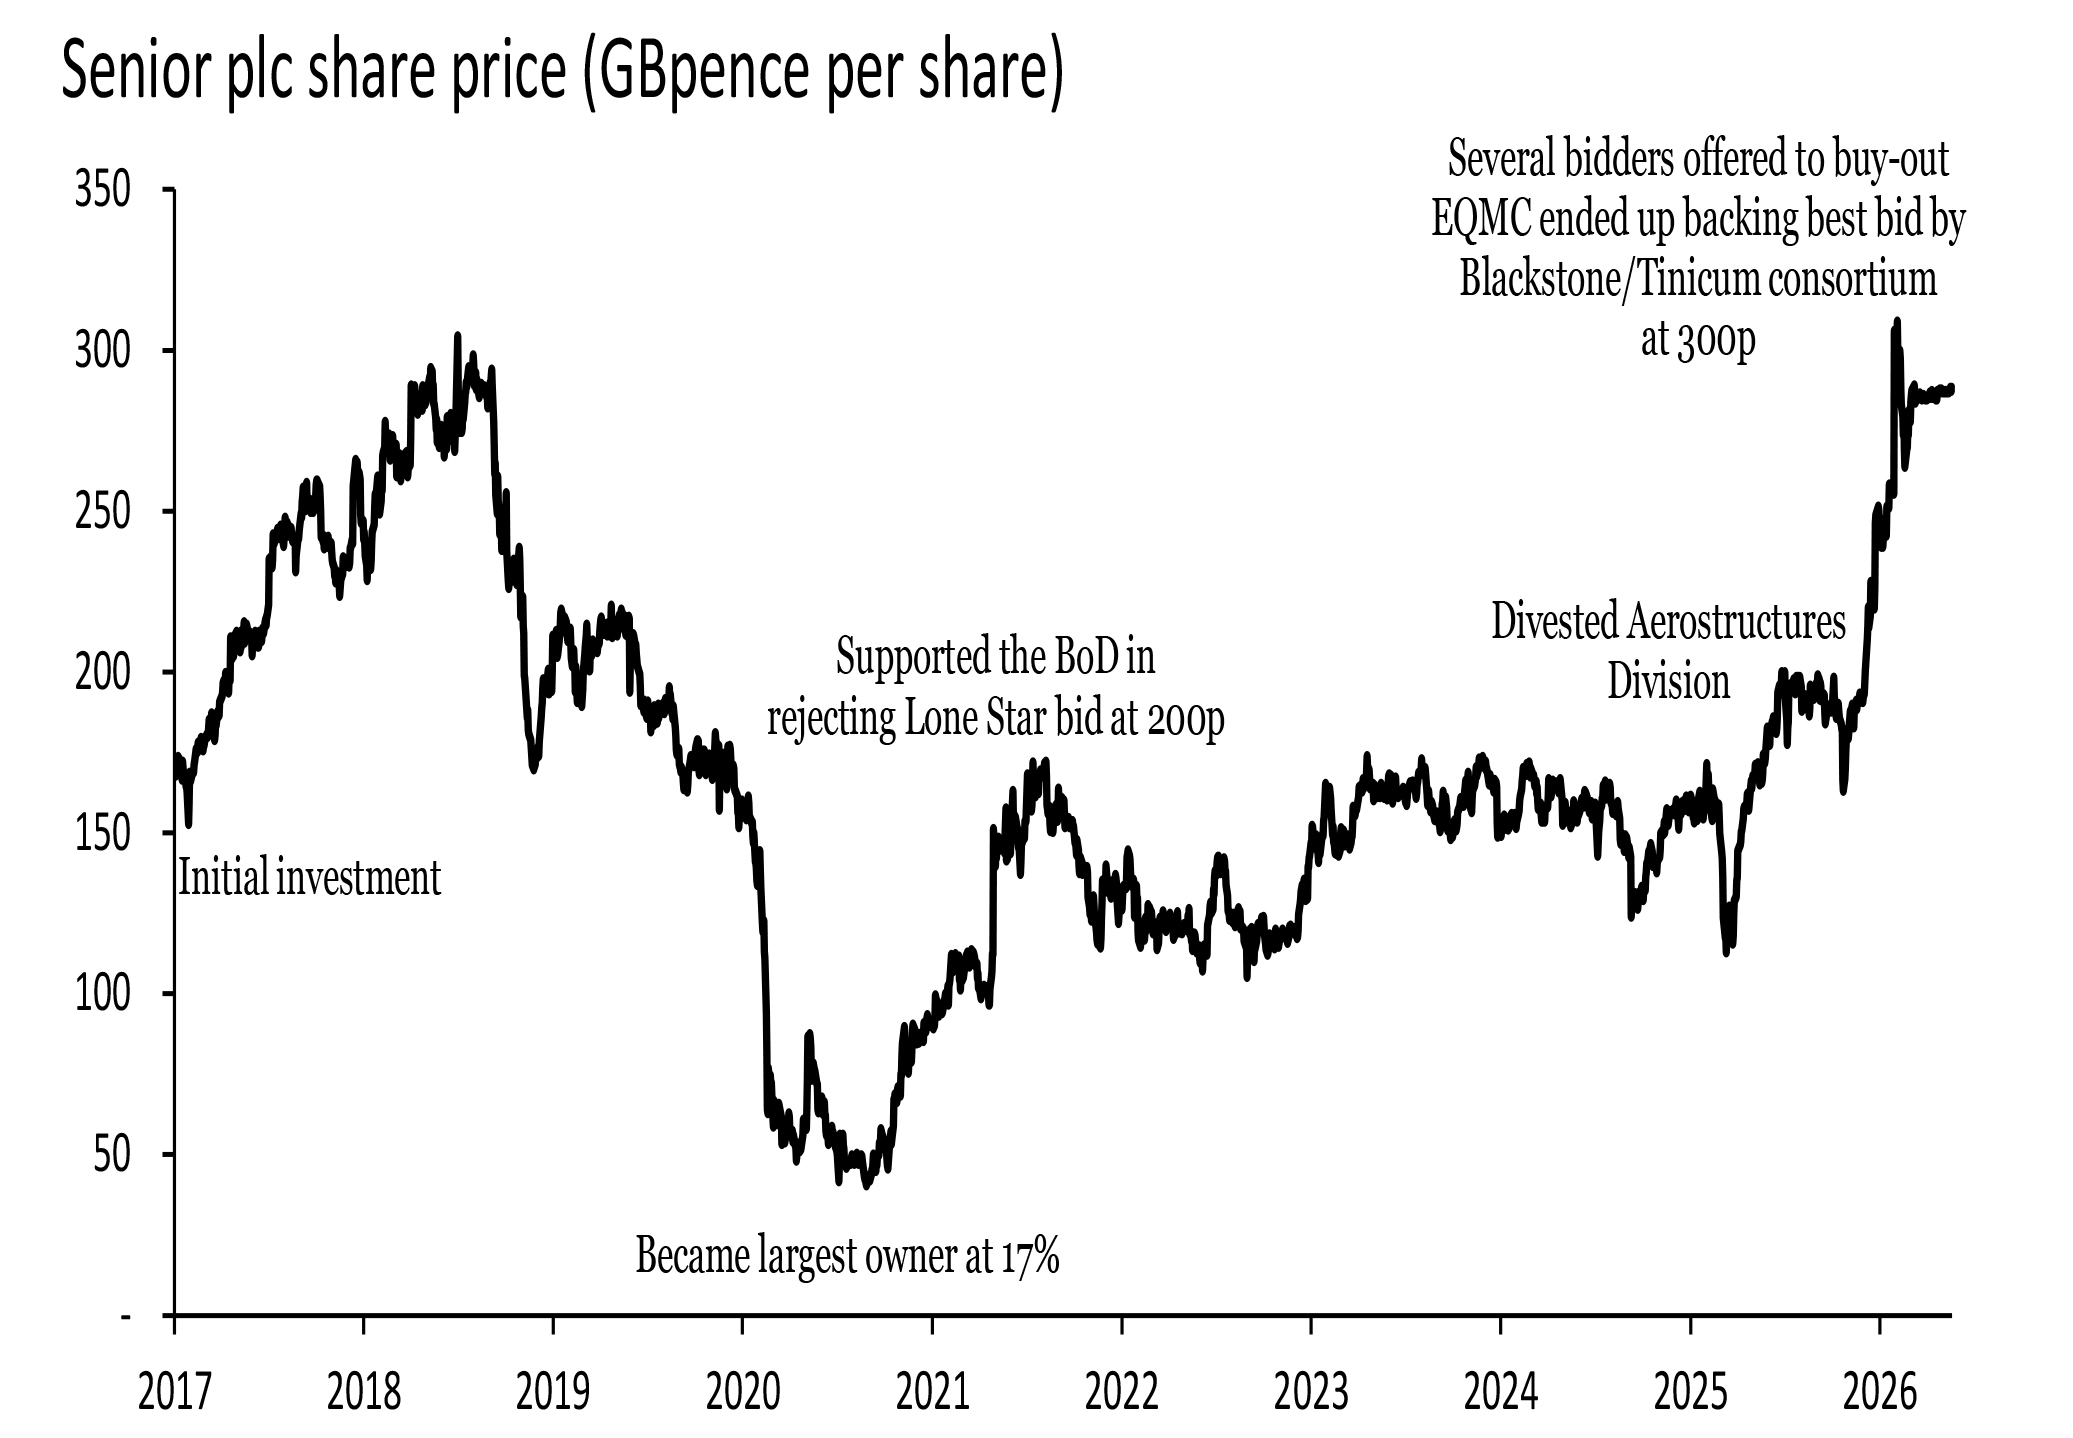
Senior plc tells the third story – conviction held through adversity. Senior makes the ducting and fluid-conveyance systems fitted to nearly every large commercial aircraft in use today, the kind of parts Boeing and Airbus cannot do without and where there is no room for error. We invested in 2017 and when COVID grounded the world’s fleets and Senior’s shares collapsed, we did not retreat because nothing about the business had actually broken. Its technology, its customers, its place in the supply chain were all intact: what had broken was sentiment. We stood firm, added to our holding and became the company’s largest shareholder. When Lone Star came knocking in 2021 with an offer timed to exploit the dislocation, we stood with the board and turned it down.
Then came the quieter work: the sale of the non-core aerostructures division, a tighter operational focus, the patient remaking of Senior into a pure-play fluid systems business of genuine quality. That work set the stage. When the buyers finally came, they came in numbers – a contest among suitors that ended this year in a recommended cash offer from a consortium of Tinicum and Blackstone, whose own aerospace holdings made them the best buyers because of the synergy potential. As Senior’s largest shareholder, with more than 17 per cent, we backed the deal and its shareholders approved it with overwhelming support. The value the public market had withheld for years was, in the end, paid in full and in cash. From COVID’s lows to a hard-won, competitive exit: there is no clearer picture of what patient, constructive ownership can achieve.
 Source: Bloomberg (price data adjusted for spin-offs and dividends)
Three companies, three paths, one idea. None of these outcomes waited for perceptions or received wisdom to change. Each was made, not found. That is the opportunity in European small caps today: not to wait for the discount to close, but to invest with those who will close it.
We have been investing in this corner of the market for more than 20 years. We have rarely seen valuation, fundamentals, sentiment and corporate activity as aligned as they are today. Contrarian opportunities of this quality usually are not available for long. The investors who act while pessimism is still at its peak are the ones who capture the full reward of what follows.