Investing in data centres is one avenue individuals have of accessing the opportunities the artificial intelligence industry is offering. Gavin Truong details some of the risks involved with this strategy.
Data centres sit at the heart of the artificial intelligence (AI) theme and an extraordinary race is on to fuel the huge demand for ‘compute’. This article sets out how we think about the global data centre sector from an investment perspective: the demand and supply dynamics at work, development risks and why we believe price discipline matters more here than in almost any other part of the market right now. Our position is not that the theme is weak, it’s that good news is already in the price and an active, selective approach is the most reliable way to participate and manage the cross-section of risks.
Spending by the largest cloud and AI providers has grown sharply since 2022 and continues at pace. The five largest companies in the space, or ‘hyperscalers’, Amazon, Microsoft, Alphabet, Meta and Oracle, are expected to spend in the order of US$700 billion on capital projects in 2026, up around 70 per cent on 2025 and more than four times 2022 levels. Roughly three-quarters of this spend relates to data centres: self-builds, leasing from third-party operators and sourcing servers and chips.
There has been genuine debate about how durable this appetite for capital expenditure will prove. Alphabet’s June 2026 equity raising of US$85 billion to fund AI infrastructure, the largest equity offering in history, in fact larger than the SpaceX initial public offering, suggests the major players remain fully committed, at least in the near term. That said, a commitment to spend is not the same as a return on that spend and the eventual payback remains unproven.
While the data centre build-out is being driven by hyperscaler demand, what’s less understood is that specialist listed data centre managers have operated successfully for years prior to the current boom and, unsurprisingly, incumbent data centre real estate investment trusts (REIT) have performed very well in recent times.
The wave of fresh capital has clearly flowed through to leasing activity. Global data centre REIT leasing volumes have grown substantially since 2022, with activity concentrated in the US. Records were smashed in the first quarter of 2026, with 4000 megawatts leased in the first quarter of 2026 versus 1300 megawatts for the whole of calendar 2021.
The scale of demand has absorbed almost all available capacity in major markets: US primary market vacancies have fallen to around 1 per cent and the Northern Virginia submarket, the world’s largest, sits near 0.5 per cent.
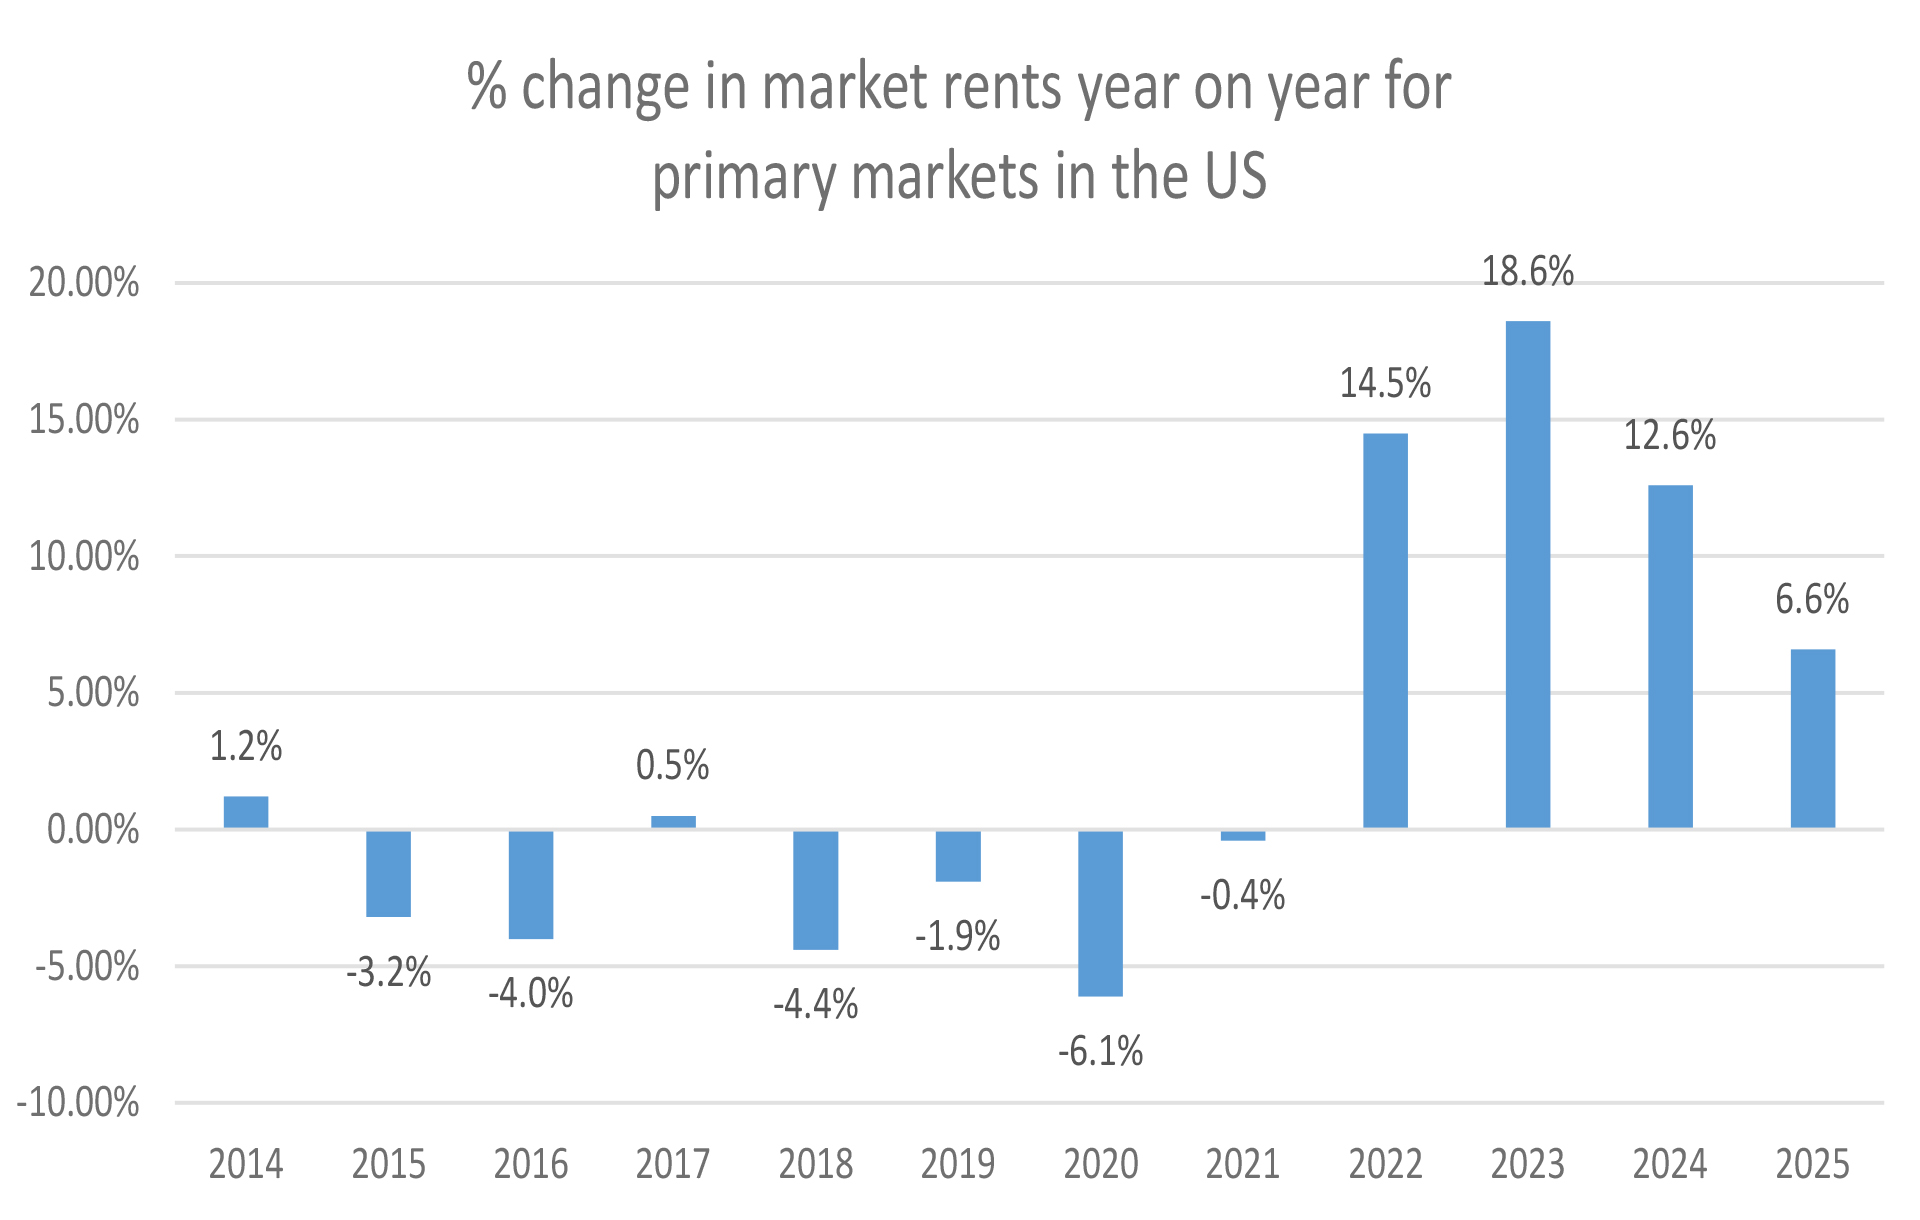
With power constraints serving as a bottleneck to bringing new data centres online (grid-connection wait times average around five years in the US and Europe, and close to three years in the Asia-Pacific), this has delivered substantial pricing power to existing data centre operators, driving strong rent growth. This upper hand marks a change from the pre-2022 period when tenants set the terms.
 Source: CBRE
This combination of rising rents and a powerful structural tailwind has produced strong returns for investors in listed data centre REITs. Since the public release of ChatGPT in November 2022, Equinix and Digital Realty, the two largest data centre REITs globally, delivered total returns of around 104 per cent and 114 per cent respectively as reported in US dollars for NYSE:DLR and NYSE:EQIX from 30 November 2022 to 31 May 2026.
Hyperscaler capital has also flowed to developers. Data centre development projects today are being underwritten at stabilised yields on cost of roughly 10 per cent to 13 per cent, drawing in a wide range of entrants, including repositioned industrial REITs, such as Goodman Group, former crypto-miners, such as Iren and Firmus, and more speculative developers.
Around 31.7 gigawatts (GW) of new data centre capacity is currently under construction globally, with 25.3GW of that in the Americas, predominantly in the US. To put that in context, it represents close to 30 per cent of existing global stock or more than US$380 billion of construction spend on our estimates. Looking further out, global data centre capacity is expected to roughly double between 2025 and 2030, from about 103GW to around 200GW – a compound annual growth rate of around 14 per cent.
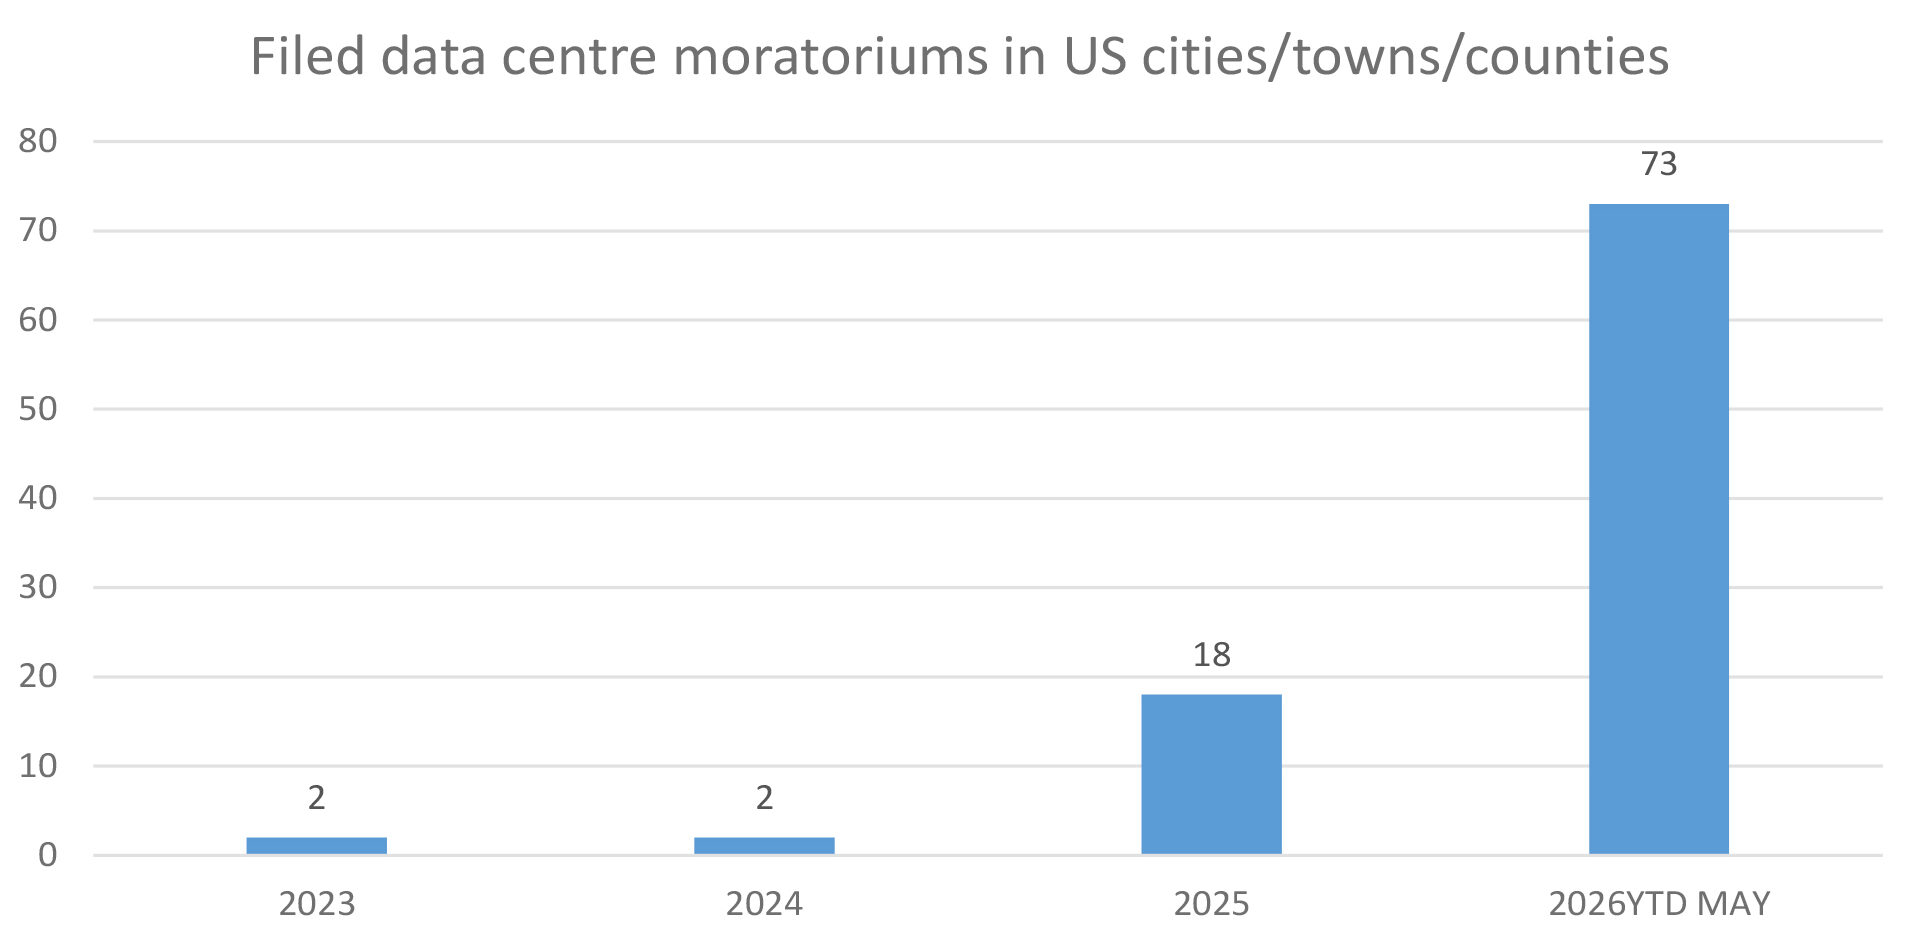
An emerging risk is growing resistance to new data centre development, driven by concerns about effects on local utility prices, environmental impact and broader ‘not in my backyard’ sentiment. As shown below, in the US this is no longer a fringe issue.
 Source: Interconnected Capital as at 31 May 2026
A recent local example of this constraint is Australian operator DigiCo (ASX:DGT) where it abandoned a planned development in Los Angeles after council and community opposition. In DigiCo’s prospectus the project had been slated to begin construction in 2025; when the project was cancelled in April 2026, a development permit had not even been granted.
In our view, this kind of pushback is a growing risk for newer and smaller operators where the market has awarded a high valuation on the assumption sizeable development pipelines will be completed and leased on schedule.
Price is always the ballast against a compelling growth narrative and on most measures the listed data centre cohort is fully priced. A high degree of development execution is arguably built into current valuations, which leaves little room for disappointment if developers can’t deliver, demand stutters, supply overshoots or policy friction increases.
Our deep experience investing across property sectors globally tells us to retain a clear-eyed read on where supply and demand dynamics can shift. It is unusual to see this much new supply scheduled for a single sector in such a short window. While the demand profile gets most commentator attention, there are nuanced and emerging risks on the supply side, including adaptation risk as chip technology rapidly evolves, input cost (for example, power prices) risk and even stranded asset risk.
We view property developers within any property sector with extreme caution, with the starting principle that if it’s not earning rent, risks are higher. The same risks are on full display for listed data centre operators with large development pipelines. Coupled with full valuations and a dynamic operating environment, we believe caution is required.
The principles above equate to data centre REITs making up only a modest part of our portfolios and why the sector is a smaller share of our holdings than its approximate 11 per cent weight in the global REIT index. That positioning is not a bet against the theme. It reflects our view that, at today’s prices, we can find more attractive risk-adjusted opportunities elsewhere in global real estate, where growth is less fully appreciated and the margin of safety is wider. Examples of these include senior housing and retail in the US, all of which are experiencing fundamental undersupply leading to significant rent and earnings growth.
Our preference within the data centre universe is for operators with large, established, US-centred portfolios that are already generating income, bought at the most reasonable valuation we can find. Our core data centre holding, Digital Realty (NYSE:DLR), illustrates this: DLR operates more than 300 data centres, over 100 in the US, and trades on an earnings before interest, tax, depreciation and amortisation multiple of around 21 times, against relatively small local names such as DigiCo (around 22 times) and NextDC (around 49 times). We also believe incumbents with large, already-operating US portfolios will be well positioned should there be further delays in new supply.
Data centre REITs have, to this point, wholly benefitted from the AI pile-on. To us, the sector in aggregate appeals given the demand-supply imbalance, but where we believe careful stock selection is required is with listed data centre operators with large development pipeline execution risk, a substantial risk that exists for all players, and the full (if not stretched) pricing for the sector.
We do not think the answer is to avoid the sector, nor to chase it. We think it is to be selective, to favour quality and existing cash flow over promise, to insist on a sensible entry price and to keep the sector in proportion to other opportunities across the listed real estate universe. In a part of the market priced close to perfection, discipline is what protects investors when the story meets reality.