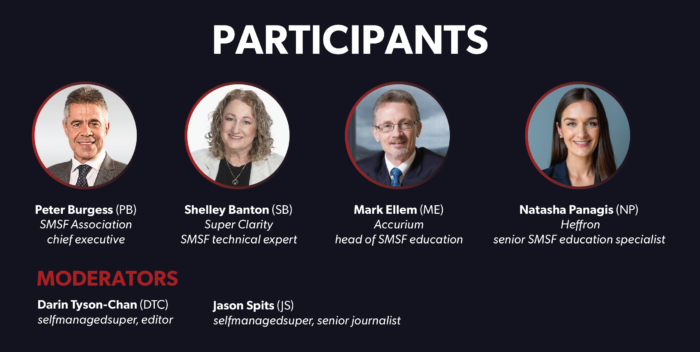
The SMSF sector has faced another year of changes, many of which were topics addressed at the selfmanagedsuper 2026 SMSF roundtable. In the first segment of the discussion, the next wave of change via a raft of new consumer protection measures was front and centre.
DTC: In general, what do we think about the SMSF reforms Financial Services Minister Daniel Mulino announced recently?
PB: There is a lot of detail to come, so for the measures specifically relating to SMSFs it is difficult to form a judgment as to how effective they are going to be. We pushed hard for measures that addressed conduct, rather than measures which impose additional limitations on funds, focusing on the misconduct that has given rise to consumer loss. You can see elements of that in what was announced by the Minister. Some of those measures address the high-risk lead generation activities, which was good to see, and other measures are designed to give the regulators more power to be proactive. We have been critical in the past of them being slow to act, so being able to be more proactive in enforcing the law is a good thing.
NP: The devil is going to be in the detail in terms of how these are going to work and a key area involves the ATO stopping rollovers into new SMSFs. We all understand this one was announced so it can investigate concerns of fraud, misconduct and consumer harm. However, anybody who has helped clients roll over money from a large Australian Prudential Regulation Authority (APRA)-regulated super fund to an SMSF knows that process can be long, so in practice you have to ask: how is it going to work? How is the ATO going to intervene here? We want to make sure the regulator can identify a genuine risk before somebody rolls their super benefits over into an SMSF because it is a very different proposition from trying to recover that money afterwards. It comes down to how the ATO is going to intervene, which is a much cheaper and more effective option than going down the Compensation Scheme of Last Resort route once it all goes pear-shaped. But we don‘t want it to add more red tape and extra burdens to legitimate transfers, particularly those that are advised.
SB: We want to make sure anything that has been put in place is actually going to be preventative in the future. We don’t want to see more compliance requirements as a reactive measure. It must be based and predicated on the authorities having a well-founded suspicion of consumer harm, but what does that actually mean? I don‘t think anybody in principle would be against these measures being implemented, but it is finding out how it is going to play out, what barriers it is going to put in place to setting up SMSFs and how it is going to help trustees at the end of the day in terms of making sure their money stays safe and secure.
ME: What will be the mechanism for identifying a rollover that is at risk separate from the ATO’s current powers to not register an SMSF in the first place? Most rollovers happen at the time you set up the SMSF, so if the ATO says it is okay to register that fund, then what changes from that point to the first rollover making the last action a problem? How are they going to identify it? Is this going to create a delay? SuperStream is supposed to make rollovers quick, so how are they going to identify an at-risk rollover within that system?
DTC: To that end, is there a danger the measure might encourage industry funds to flag something suspicious and have the ATO prevent an SMSF establishment to manage member outflows?
PB: It is possible and we won’t know until we see the criteria the ATO are going to use. The words the Minister used were “well-founded suspicion of consumer harm” and we don’t know exactly what that means, so there is that concern. Treasury put out a dashboard impact analysis document to specifically look at the announced SMSF measures, which mentioned the ATO only has limited powers to withhold the compliance status of an SMSF and it has to wait for a contravention to occur before it can step in and do anything. Through the Australian business number (ABN) application process, there are prescribed circumstances when it can stop the issuing of an ABN, otherwise it is obligated to issue that number, but the Super Fund Lookup service can be used to withhold the compliance status of a fund. I suspect that is what it is going to do here with this new power and use that service to withhold the compliance status if it has concerns about various things. To answer your question, we are concerned about the prevention of rollovers and that is why the detail will be really important.
NP: There is going to need to be some clear criteria and review rights where rollovers are blocked or delayed and the question is whether the ATO can accurately identify these high-risk cases without slowing down legitimate transactions or rollovers. What intelligence is the ATO going to use to identify risky rollovers and what rights will members have if their rollover is delayed?
SB: I am interested in how the government and ATO are going to program this in and what criteria is to be used so we know there is some tangible evidence behind rollover action rather than suspicions or ulterior motives the APRA funds might have in terms of retaining those member balances in their accounts. We don’t have enough answers at this point in time, which is surprising because the Minister made these announcements in August and since then all we have heard is crickets.
DTC: Does the recent track record of regulators with regard to the Dixon Advisory, United Global Capital, Shield and First Guardian collapses cause concern over the potential effectiveness of this measure?
SB: What is happening with these scams and fraud the regulators are trying to prevent at the moment is much of it has been generated through artificial intelligence (AI) and organised criminals are actually using it to steal money. AI-generated scams are four times more effective than anything else so the regulators are playing whack-a-mole trying to catch up to what is happening out there. In light of that, we want these measures to be realistic and practical. They need to be looking at situations that are going to be preventive, not reactive or representing lip service to the situation which we are finding ourselves in, unfortunately, more and more within the superannuation industry.
PB: We are very supportive of enhancing consumer protections across the superannuation industry, but we need balance between choice and new measures which restrict people’s right to choose. That is what we are trying to find with this package. We have been critical of the regulators not being proactive enough in identifying this misconduct, but they may well come back and say: “This is what proactive regulation looks like because upon examination you can link some of these behaviours together.” We know they are going to be looking for things like rollover prevention powers, as well as a requirement to collect data on the intermediaries involved in the establishment process. We will have to inform the ATO about the advisers, or other intermediaries, who are part of the establishment process, and with investment strategies there has been some talk about having to provide those to the regulator as well. When you look at these things and put them all together, does this give the regulators a better picture to be proactive in identifying this misconduct? Possibly yes, but we have to get the right balance between achieving that, but also not imposing unreasonable restrictions on people that want to exercise choice.
Darin Tyson-Chan
Editor
Darin is the founder and publisher of Benchmark Media, an independent publishing house whose mastheads include financialobserver, selfmanagedsuper and smstrusteenews. He has been covering the financial services space for over a decade and in this time he has worked for a variety of trade publications. Darin has also written for the Money section published in The Sydney Morning Herald and The Age.
Articles by Darin
Jason Spits
SENIOR JOURNALIST
Jason is a senior journalist with Benchmark Media and writes for the selfmanagedsuper website and magazine and smstrusteenews website. He has covered financial services since 1999 and has written about life insurance, superannuation, investment management and financial advice, in both a freelance and in-house capacity, and also did a brief stint as a media manager for an industry association. He has been the editor of trade titles Money Management and Financial Standard, and was most recently senior journalist with life insurance title Riskinfo.
Articles by Jason